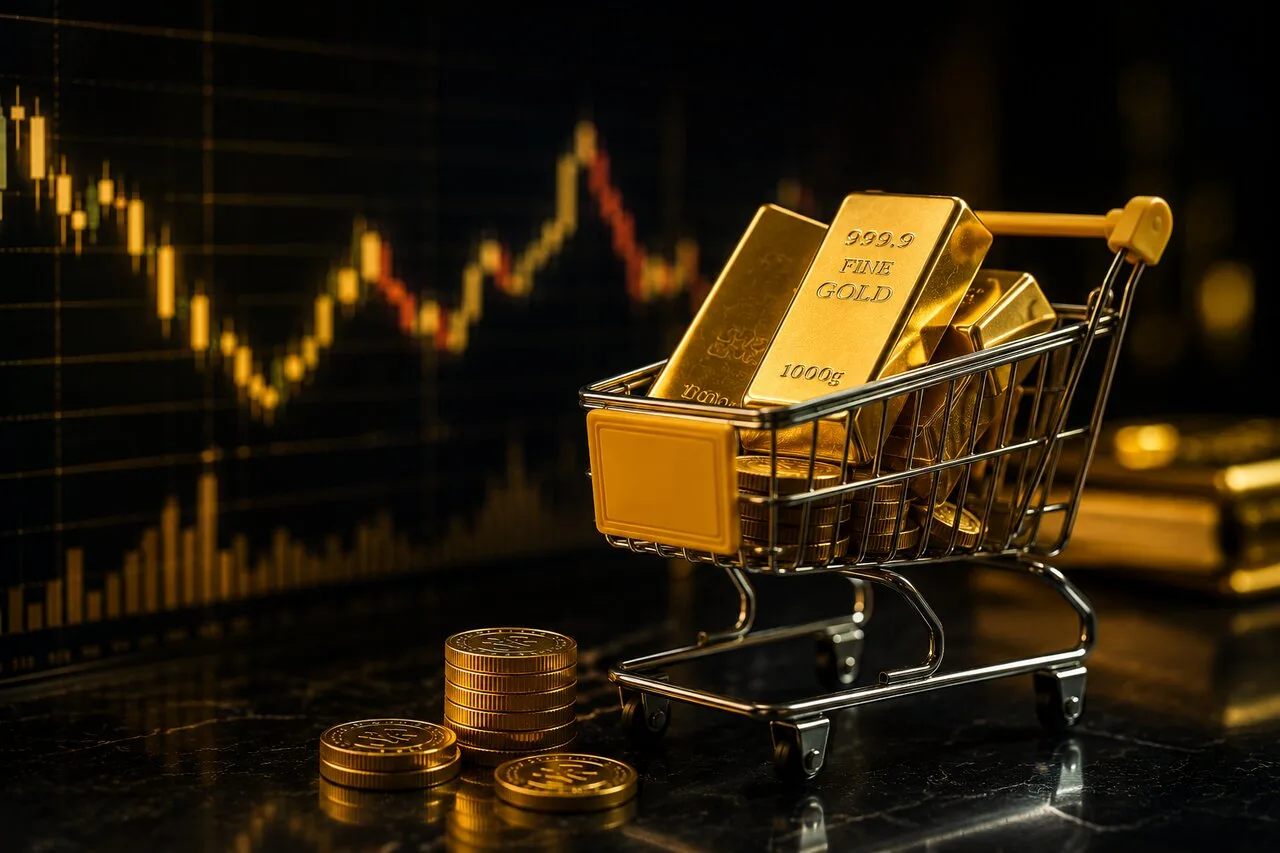
Liquidity provision with gold assets in 2026 has become one of the significant challenges for households. When the need for immediate liquidity arises, selling gold means losing a valuable asset and an inflation hedge that has helped families over the years.
Challenges of Selling Gold and Alternative Solutions
According to reports, tens of thousands of billion tomans worth of gold in the form of jewelry, coins, and bars are kept in Iranian homes. This asset has acted as an inflation hedge over time. However, at various points in life, families face a dilemma: keeping gold to preserve value or selling it for immediate liquidity. Costs of dowries, medical treatment, business development, and investment opportunities are among the reasons that drive families to sell gold.
The simplest way to secure liquidity is to sell gold; however, this may prevent the family from benefiting from the future price growth of gold. In inflationary conditions where gold prices increase by 40 to 60 percent annually, selling gold means losing a growing asset.
Methods of Securing Liquidity with Gold Collateral
One effective method is gold pawning. In this method, gold is used as collateral while ownership is retained. Various financial centers offer facilities backed by gold. These centers typically provide loans amounting to 60 to 80 percent of the current value of gold, with annual interest rates ranging from 4 to 23 percent.
Official centers and galleries that are members of the Gold and Jewelry Union also provide liquidity services, but the main difference lies in the valuation basis. While official centers operate based on a fixed approved ceiling, galleries value based on the current market price.
To choose the appropriate method, it is essential to examine the advantages and limitations of each. In cases where immediate liquidity is needed while retaining ownership of gold, pawning gold is considered a suitable option. Additionally, many centers offer these services without the need for a guarantor, only requiring a national ID card.
Ultimately, the choice of liquidity provision method depends on each family's priorities. In 2026, given the economic conditions and market fluctuations, awareness of available methods can help families make better decisions.